
Benefits OnLine
- Rating
- 3.5
- Downloads
- 1.00M
- Content Rating
- Everyone
Benefits OnLine - Screenshots
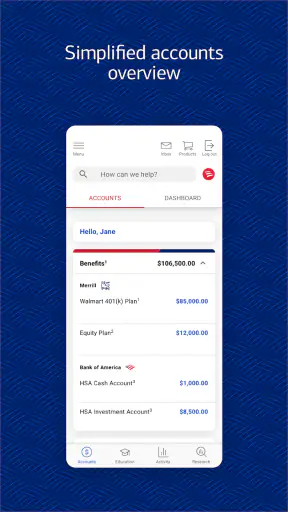
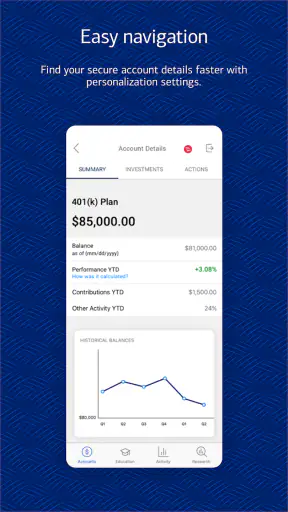
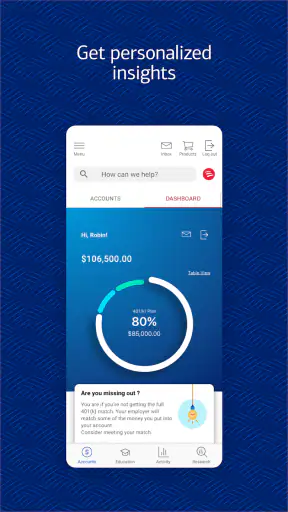
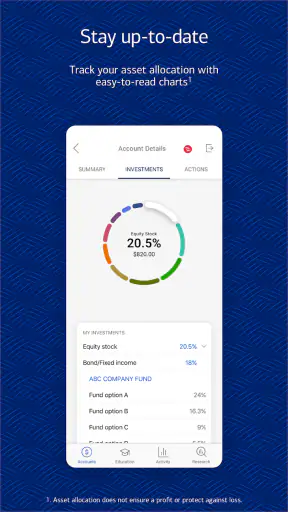
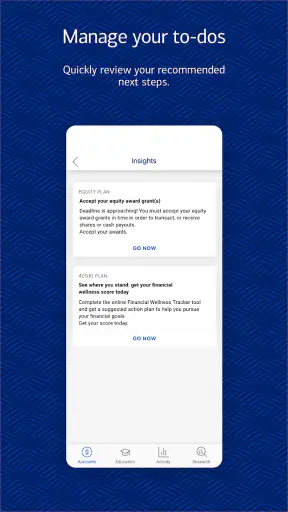
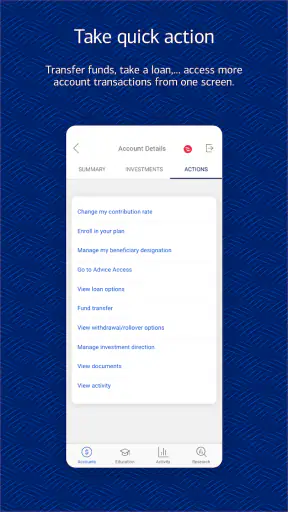
Pros
- Centralizes employee benefits
- balances
- and program information in one app.
- Quick access to benefit details without needing a desktop browser.
- Useful notifications can remind users about deadlines and account activity.
- Secure sign-in options help protect sensitive personal and benefits data.
- Available on mobile devices
- making benefit management convenient while traveling.
Cons
- Features depend on the employer’s Benefits OnLine configuration and available programs.
- Some users may need help from HR when account or enrollment issues arise.
- The interface can feel crowded when many benefit categories are enabled.
- Certain actions may redirect to web pages instead of staying fully inside the app.
- Requires an internet connection for most account and benefits information.
Benefits OnLine - Description
- App Name
- Benefits OnLine
- Package Name
- com.ml.mobile.bol
- Developer
- Merrill Lynch, Pierce, Fenner, and Smith Inc.
- Category
- Finance
- Last Updated
- Oct 1, 2018
- Version
- 26.08.02
Managing workplace retirement and benefit information is rarely something I want to do for fun, but it is exactly the kind of task that becomes stressful when the right details are scattered across emails, paper statements, and an employer portal. Benefits OnLine is built for that narrow job. Developed by Merrill Lynch, Pierce, Fenner, and Smith Inc., this free finance app gives eligible users a mobile route into their retirement and benefit services instead of making every check require a desktop browser.
I approached it as a practical account-management tool rather than a general investing app. That distinction matters. It is not the kind of application I would choose to research the whole market, build a broad personal budget, or compare every possible investment product. Its value is more focused: when my workplace benefits are connected to Merrill’s service, I can use a phone to review the information that matters to my employment and long-term savings.
The app has a 3.5 average from roughly 3,400 ratings and more than a million installs, so it is clearly used beyond a small group of early adopters. It is rated for Everyone, costs nothing to download, and currently appears as version 26.08.02 for devices running iOS or Android 11 and later. Those details make it accessible to many employees, although the useful experience still depends heavily on whether my employer’s plan is supported and what services my particular account includes.
How Benefits OnLine fits into everyday benefit management
A focused companion for employer-linked accounts
The first thing I noticed about Benefits OnLine is its purpose-built nature. The app is centered on retirement and benefit services provided through Merrill Lynch, rather than trying to become a complete financial dashboard. That focus can feel limiting if I expect one app to show every bank account, credit card, insurance policy, and investment in one place. On the other hand, it avoids the clutter that often appears in broader personal-finance applications.
For an employee, the most useful moment is usually not a dramatic financial decision. It is a small question that needs a quick answer: Am I contributing as expected? Is my workplace plan information up to date? Do I need to review something before an enrollment deadline? Having a dedicated mobile entry point can make those checks easier to fit between other tasks, especially when I do not have access to a laptop.
I would describe the app as a service window rather than a financial coach. It helps me reach information connected to my benefits relationship, but I should not expect it to replace a conversation with a qualified adviser or the plan documents supplied by my employer. That is an important boundary. The app can make account access more convenient, but convenience does not automatically make a retirement decision simple.
A realistic use case during a busy workday
Imagine that I receive a workplace message reminding me to review my retirement contribution before an internal deadline. Instead of waiting until I get home, I can open Benefits OnLine from my phone, sign in, and check the relevant account information while taking a short break. If the displayed details answer my question, the task is finished in minutes. If something looks unfamiliar, I have identified the issue early enough to consult my employer or Merrill support rather than discovering it after the deadline.
That workflow is more valuable than it sounds. Retirement administration is full of small delays: forgetting a password, losing a statement, or postponing a review because the desktop site feels inconvenient. A mobile app lowers the effort needed to begin. My practical tip is to use it for short, defined checks rather than opening it without a purpose. Before signing in, I decide whether I am checking a balance, reviewing plan information, or following up on a benefits task. That keeps a quick visit from turning into unfocused scrolling.
Where it compares well with broader finance apps
General money-management apps are often better when I want a consolidated view of household spending or accounts from several institutions. They may offer budgeting categories, cash-flow summaries, and a wider financial picture. Benefits OnLine has a different advantage: it is tied to the workplace retirement and benefits relationship instead of asking me to assemble that context from separate sources.
Compared with using a mobile browser, a dedicated app can also feel more direct. I do not need to search for the correct portal each time or navigate through unrelated pages. The trade-off is that a browser may be more flexible when I need a full document, a larger workspace, or access to an employer page that is not represented in the mobile experience. I would keep the browser option available even if the app becomes my normal first stop.
What the current version means for existing users
The significance of version 26.08.02
The current version is 26.08.02, which tells me the product is still being maintained as an active mobile service rather than left as a one-time portal wrapper. I treat that as a useful sign of ongoing product attention, but I do not read a version number as proof that every part of the experience has changed. Without a detailed change history, it would be misleading to claim that a particular screen, workflow, or security process was added in this release.
For someone already using the app, the sensible approach is to update through the normal device store process and then check the tasks I actually perform. I would verify that I can still reach my account, locate the information I use most, and complete any important action before relying on the app during a deadline. This is especially worthwhile after an update because a familiar menu can move even when the underlying service remains the same.
The app was released on October 1, 2018, so its current form sits on top of several years of service life. That history can be reassuring for users who prefer an established benefits channel, but it also explains why the interface may not feel as modern or unified as a newer consumer-finance product. A mature app often prioritizes continuity and account access over visual novelty. In my view, that is acceptable here as long as the important information remains easy to find.
What the rating suggests without deciding the issue
An average of 3.5 from about 3,400 ratings gives me a mixed signal rather than a simple recommendation. The app is clearly useful to many people, yet the score also suggests that some users encounter friction. With a little over 1,100 written reviews, there is enough user feedback activity to show that the experience is not universally smooth.
I would not interpret that rating as a judgment on retirement services themselves. Finance apps are unusually sensitive to login problems, account-linking issues, employer configuration, and time-sensitive transactions. A person who cannot access a benefit account when needed will understandably have a much harsher view than someone who only checks information occasionally. My own recommendation is to judge the app by the specific task I need to complete, not by the average score alone.
A better setup routine than simply installing it
After installing Benefits OnLine, I would first confirm that my employer’s retirement or benefits arrangement is the one connected to the service. Then I would sign in when I have enough time to resolve any access issue, rather than waiting until a contribution or enrollment deadline. I would also identify the official support route associated with my plan and keep that information separate from the app. If the app becomes unavailable, I should still know where to ask for help.
Another useful habit is to compare the information shown in the app with a recent statement or employer communication during the first few visits. This is not because I expect the app to be inaccurate, but because it helps me learn which labels correspond to my plan. Retirement terminology can be easy to misunderstand, particularly when contribution types, employer benefits, and investment choices appear close together. A few minutes spent learning the layout can prevent a rushed interpretation later.
Where the experience may still feel restrictive
The biggest limitation is its narrow scope. If I want a complete household financial picture, Benefits OnLine is not the right central dashboard. I would need another tool for everyday spending, emergency-fund planning, debt tracking, or accounts held elsewhere. Even within retirement planning, the app should be treated as a way to access plan-related information, not as a substitute for understanding fees, tax treatment, investment risk, or the rules that govern my employer plan.
There is also a practical difference between viewing information and acting on it. A mobile screen is convenient for a quick review, but it may be less comfortable when I need to read lengthy disclosures or compare several options carefully. For those decisions, I prefer a larger screen and enough uninterrupted time. The app is strongest at reducing access friction; it is less compelling as the only environment for detailed research.
Users who do not have a Merrill-connected workplace benefit relationship should probably skip the installation. The app’s category and purpose are specific, and downloading it merely to explore general retirement tools is unlikely to be worthwhile. Likewise, someone looking for a simple budgeting app will be better served by a product designed around spending and cash flow rather than employer benefits.
Three practical trade-offs worth knowing
- Convenience versus context: the phone makes a benefits check quick, but a small screen can encourage me to act before I have read the surrounding explanation.
- Dedicated access versus broad coverage: the app keeps employer-linked information in one focused place, while a general finance app may show more of my overall financial life.
- Established service versus modern feel: its long operating history can support continuity, but the interface may not match the polish of newer consumer-finance applications.
A fourth trade-off is worth adding: speed versus verification. I can open the app quickly when a workplace reminder arrives, but I should still compare important changes with the plan communication or statement that explains them. That small extra step is especially useful when I am changing a contribution or making a decision with long-term consequences. The app can help me respond promptly without giving me a reason to skip careful reading.
Who should use it and who should choose something else
I think Benefits OnLine is a sensible choice for employees whose retirement or benefit services are connected to Merrill Lynch and who want convenient mobile access. It suits people who check their workplace accounts periodically, need to respond to employer reminders, or dislike relying on a desktop browser for routine account administration. It is also a reasonable companion for someone who already has a broader budgeting app but wants a dedicated place for employer-related information.
I would choose a different option if my main goal is financial aggregation, detailed retirement education, or active portfolio analysis across several providers. A browser may be preferable for document-heavy work, while a full personal-finance platform may be better for household planning. Someone who rarely uses mobile apps and already has a reliable desktop routine may gain little from adding another sign-in. The best reason to install this one is a real need to reach a supported workplace benefit account from a phone.
What I would watch in future updates
When future versions arrive, I would pay attention to whether everyday tasks become easier to locate, whether account information is presented with enough explanation, and whether the app remains dependable during employer deadlines. I would also look for clearer movement between retirement information and other eligible benefits, provided that those services are part of a user’s plan. Those improvements would matter more to me than cosmetic redesigns.
I would also watch how the app handles the balance between quick access and responsible decision-making. A useful update should reduce unnecessary steps without making important financial actions feel casual. Clear labels, understandable confirmations, and easy access to supporting documents would help users avoid mistakes. Because the application serves a specific workplace context, improvements that respect plan differences would be more valuable than a one-size-fits-all interface.
My final view is that Benefits OnLine is a practical, focused finance app rather than an all-purpose money manager. Its free access, established service history, and mobile convenience make it worthwhile for the employees it actually serves. I would recommend it to a friend who needs a simpler way to check Merrill-linked retirement or benefit information, with one condition: use it as an access tool, not as the entire decision-making process. For quick account checks it can save time; for complex choices, I would slow down, read the plan material, and use a larger screen or appropriate human support when necessary.
FAQ
What is Benefits OnLine, and what can I use it for?
Benefits OnLine is a mobile service that gives eligible users access to information and tools related to their workplace benefits, retirement plans, savings accounts, or other employer-sponsored programs. After signing in, you may be able to review balances, monitor contributions, check investment information, read plan documents, and access educational resources. The exact features depend on your employer and the plans connected to your account.
Who can use the Benefits OnLine app, and how do I sign in?
The app is generally intended for participants in eligible employer-sponsored benefit or retirement plans. You normally need an existing Benefits OnLine account or credentials provided through your employer or plan administrator. During sign-in, the service may request additional verification, such as a security code or biometric authentication. If your employer does not participate, or your account has not been activated, the app may not provide access.
Can I check my retirement balance and manage my investments through Benefits OnLine?
For supported plans, Benefits OnLine can provide a convenient way to view retirement balances, contribution activity, investment allocations, and transaction history. Some users may also be able to change contribution percentages, adjust investment choices, or initiate eligible transactions. Available actions vary according to plan rules, account status, and employer settings, so the app should be used as a management tool rather than a replacement for reviewing official plan documents.
Is Benefits OnLine safe for viewing personal and financial information?
Benefits OnLine is designed to protect sensitive account information through account authentication and security controls, but users should still take precautions. Download the app only from an official app store, keep the operating system updated, use a strong unique password, and avoid signing in over unsecured public networks. Never share verification codes or login details. If you notice suspicious activity, contact the official support team or your plan administrator promptly.
What should I do if I cannot log in or find incorrect information in the app?
If you cannot access Benefits OnLine, first confirm that your username, password, and verification details are correct, then use the official recovery options if available. Temporary service interruptions, employer enrollment changes, or account restrictions can also affect access. For incorrect balances, missing contributions, or unfamiliar transactions, compare the information with your latest statements and contact your employer’s benefits department or the official Benefits OnLine support channel.


